The AI investment cycle is echoing past bubbles, with capital deployment outpacing proven returns.
Reported earnings strength may mask weakening free cash flow.
The next phase will be defined by monetisation, not infrastructure spend.
The AI investment cycle is echoing past bubbles, with capital deployment outpacing proven returns.
Reported earnings strength may mask weakening free cash flow.
The next phase will be defined by monetisation, not infrastructure spend.
The parallels between the dot-com and telco bubble and today’s AI wave are increasingly difficult to ignore. Valuations at record highs, a near-religious belief in technological transformation, and the promise of boundless future earnings have all been seen before. The parallels extend to the enormous capital intensity of this moment - massive investments into data centres, chips, and infrastructure - underpinned by an unquestioned conviction that AI will reshape every corner of the economy.
Yet the harder question is not whether this is a bubble, but how it ends. History - from tulips to railways to the dot-coms - suggests that technological revolutions often overshoot before finding equilibrium.
At this stage of the AI cycle, the sector has entered a symbiotic earnings phase -where spending between firms inflates reported earnings across the system -similar to the late‑1990s fibre‑optic boom. When Microsoft commits $100 billion to Nvidia’s AI chips, the transaction creates a circular prosperity: Microsoft capitalises the expenditure over several years, softening the short-term hit to earnings, while Nvidia books the profit immediately. The result is a rising tide of reported earnings among the leading AI firms—what looks like unstoppable profitability - even as free cash flow begins to flatten.
This circular reinforcement of investment and earnings sustains the illusion of perpetual growth, but it is inherently unstable. The last time this dynamic took hold, during the telecom infrastructure and spectrum bubble, earnings proved illusory once investment momentum faltered.
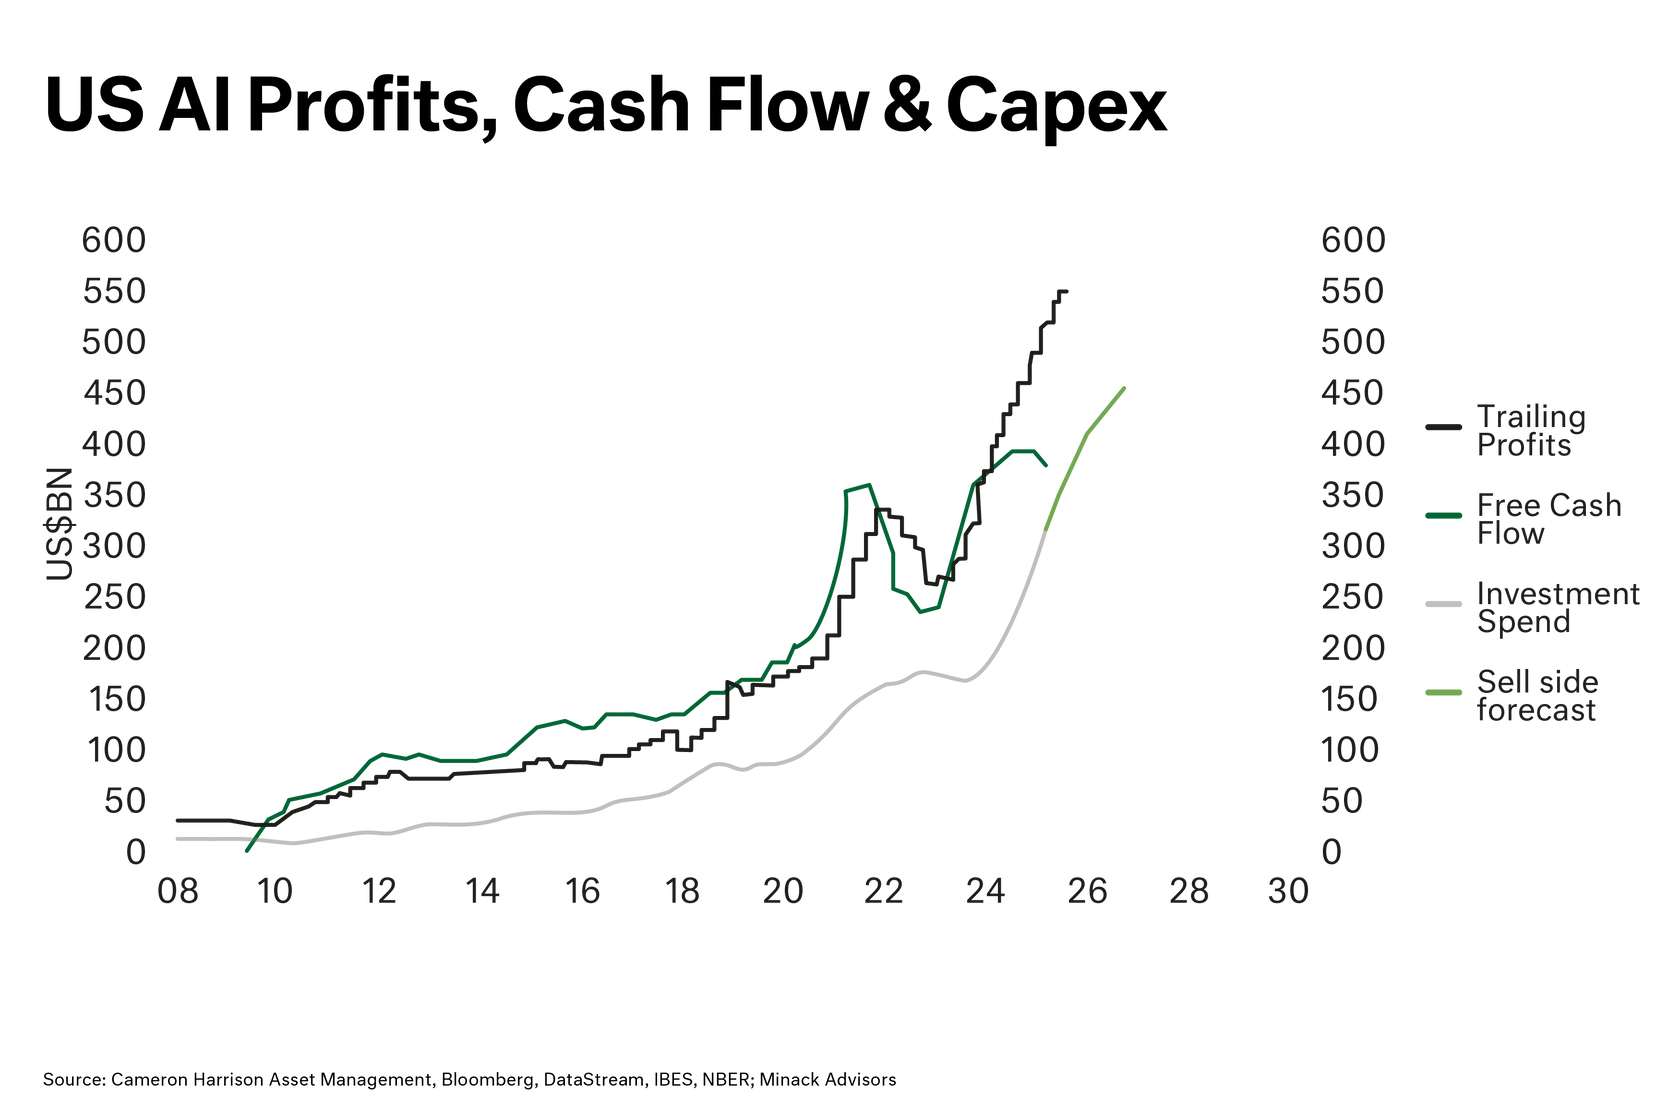
US Master winner, Rory McIlroy’s observation about golf - when I’m playing well, I can’t imagine playing badly - aptly describes market psychology. Analysts extrapolate the recent past, projecting continued exponential growth in AI investment. Consensus expectations now assume more than $1 trillion in cumulative AI infrastructure spend by end-2026.
But what does that imply for real-world economics?... If investors demand a 10% return on capital, and average gross margins are ~25% with capital assets depreciated at 10% per annum, then incremental revenue would need to rise by roughly $700–900 billion per year to justify the outlay. That is about ten times the annual revenue of Microsoft Office 365 - arguably the most successful software subscription in history.
At some point, the market will demand proof of monetisation.
Every technological revolution follows a similar arc: investment exceeds adoption, optimism overshoots cash generation, and reality re-anchors valuations. The dot-com era built the digital foundations we rely on today - but it also vaporised trillions in paper wealth before profitability emerged.
In the current cycle, the warning signs will not first appear in spending or hype, but in earnings revisions. As capital outlays continue while revenue lags, the high-beta leaders of the AI economy will begin to show margin compression. That turning point - when expectations for return on invested capital fall - will likely mark the beginning of the next regime.
For investors, the lesson is not to shun innovation but to separate infrastructure spenders from product monetisers. The winners of the next phase will be those translating AI capability into scalable, recurring cash flows - much as Amazon and Google emerged from the rubble of 2001.
History doesn’t repeat, but it rhymes: bubbles are rarely recognised from within, yet they always end the same way - when the cost of belief finally exceeds the returns of reality
Yes - both feature elevated valuations, strong capital flows, and optimistic growth assumptions. The key difference will be whether AI can convert investment into sustained, scalable earnings
The primary risk is not the technology itself, but the timing mismatch between investment and monetisation, which can pressure returns and valuation expectations.
Earnings revisions, margin compression, and evidence of revenue scaling are typically the earliest signals that expectations are shifting.
Sourced from: