What might the currency ‘tea leaves’ be predicting ahead?

Investment Solutions
By Matthew Nolan, Associate Adviser Paul Ashworth, Managing Partner, Chief Investment Officer
If capital markets had a language of their own, currencies would be their tone of voice – subtle, reactive, and often the first to change when sentiment does. The Australian dollar’s (‘AUD’) recent movements have left investors wondering what message is being sent. Are these murmurs of optimism about global growth, or warnings of a slowdown still to come? Reading currency markets is as much art as science, but when interpreted carefully, foreign exchange markets can offer a forward view on where both capital and confidence are flowing next.
Posted 24 October 2025
  • The Australian dollar is reflecting a balance between stabilising global growth and ongoing uncertainty, particularly around China.  

  • Interest rate differentials are no longer the dominant driver of the AUD, increasing its sensitivity to commodities and risk sentiment.  

  • A steady, diversified approach to currency exposure is more effective than taking directional bets in a transitioning cycle. 

Over recent months, currency markets have been quietly recalibrating. The US dollar (‘USD’), after nearly two years of dominance, has begun to soften as investors anticipate a gentler phase of the Federal Reserve’s (‘Fed’) policy cycle. The shift hasn’t been dramatic, but it marks an inflection point from an environment driven by rate-hiking urgency to one focused on managing a controlled slowdown.

Closer to home, the AUD has been testing the upper end of its recent range, hovering between US 65-67 cents. Its movements have mirrored the ebb and flow of global risk appetite. Firmer commodity prices and a modest pickup in Chinese stimulus headlines have provided support, while softer export data and lingering doubts about China’s property sector have kept enthusiasm in check.

This relationship between commodity prices and the AUD remains clear (see chart below). When real commodity prices strengthen, the AUD typically follows, and vice versa. That link is evident again in recent months as both have stabilised after a period of weakness, hinting at renewed confidence in global demand, but also underscoring the AUD’s sensitivity to shifting growth expectations.
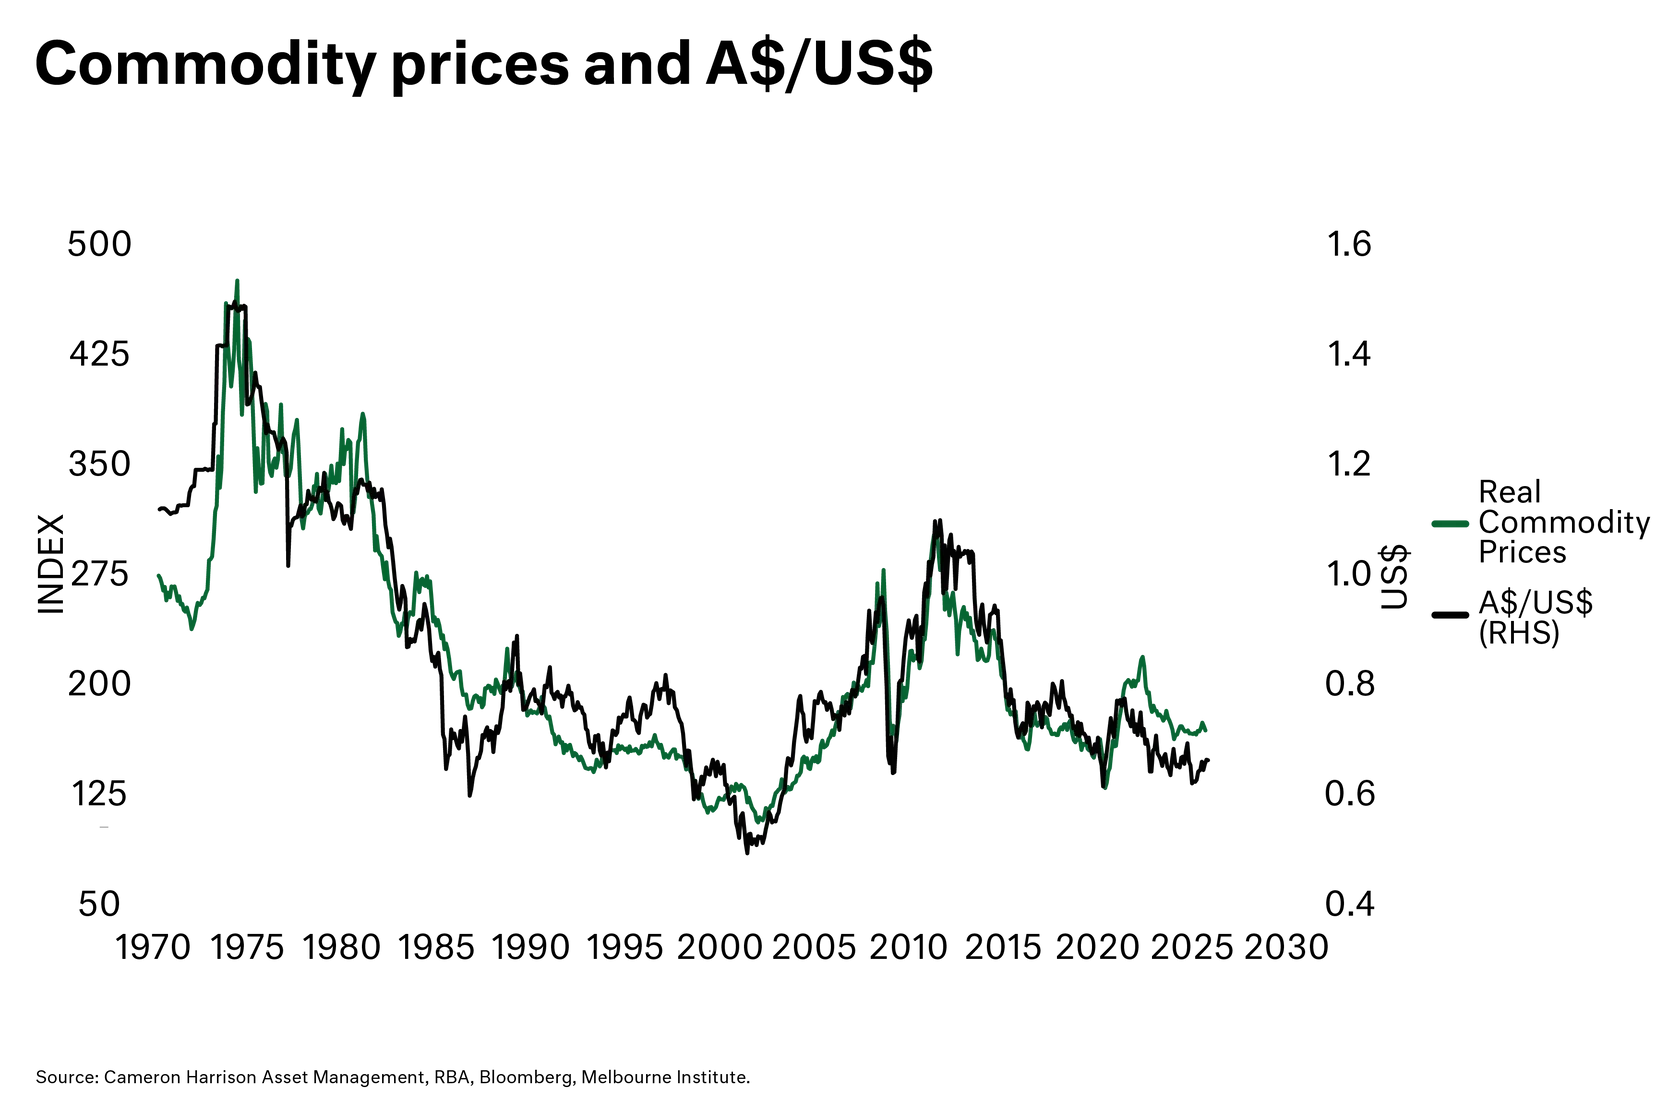
Graph - Commodity prices and A$/US$

Elsewhere, the Japanese yen (‘JPY’) remains under pressure as the Bank of Japan cautiously shifts toward normalising policy after years of keeping rates near zero, while the euro (‘EUR’) has steadied after a turbulent start to the year. For now, the market’s message appears balanced rather than bold. The USD’s strength is tiring but not collapsing, while the AUD is firming but still range-bound.

Behind the recent currency shifts lie three familiar forces: interest rates, growth, and risk sentiment. The Fed is edging from tightening to easing, which has started to take the gloss off the US dollar. The Reserve Bank of Australia (‘RBA’), by contrast, remains cautious, keeping the cash rate steady amid sticky services inflation – a stance that’s lent the AUD some support. The weaker employment outlook may, however, see earlier rate cuts for November, when markets had put this out to 2026. This is seeing downward pressure on the AUD/USD.   

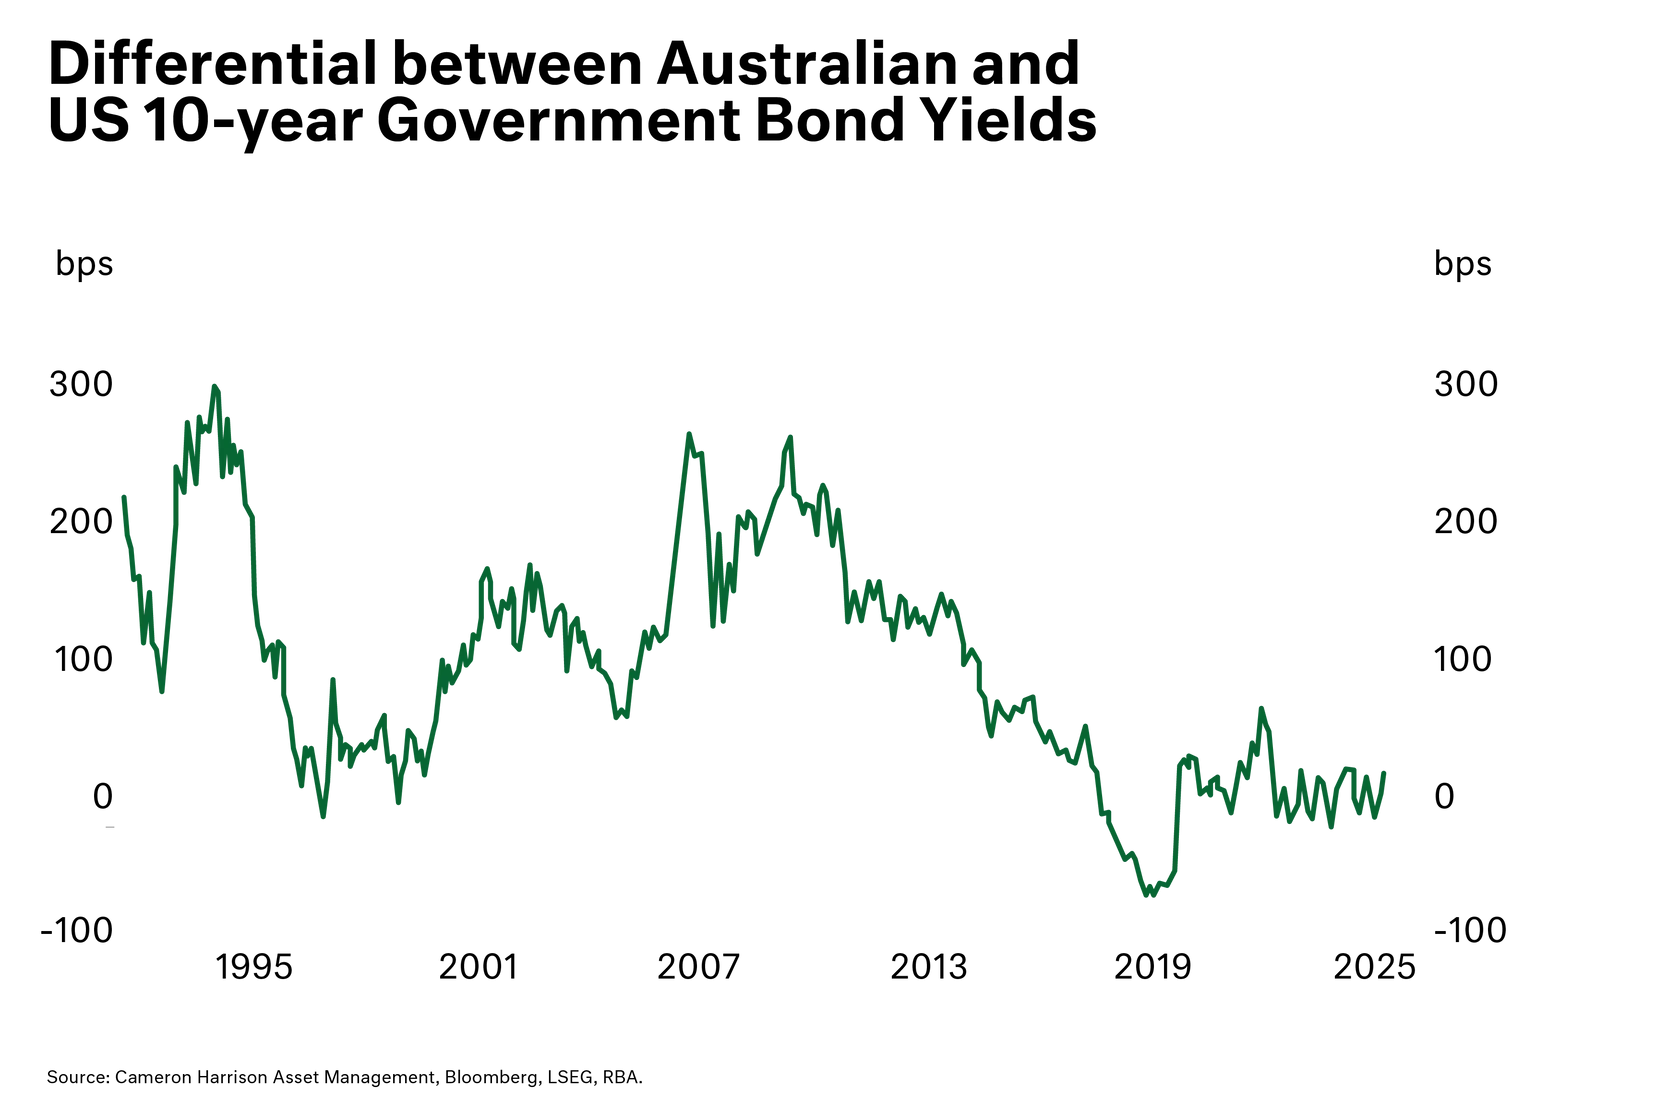
For decades, Australian bonds offered investors a reliable yield premium over US Treasuries, a structural advantage that underpinned the AUD. That premium has now largely disappeared, and despite the headwind faced during Covid, appears to be moderating (see below). The playing field has levelled, leaving the AUD more sensitive to shifts in growth, commodities, and risk appetite than to rate differentials alone.

Graph - Differential between Australian and US-10 year government bond yields

The currency ‘tea leaves’ suggest a world in transition rather than at a turning point. The USD appears past its peak but still holds safe-haven appeal, while the AUD is steady within its range, waiting for clearer signals from China and the RBA.

If global growth stabilises and rate differentials remain balanced, the AUD could drift modestly higher, supported by firmer commodity prices and a fading dominance of the USD. It’s not a call for exuberance, but a sign that the cycle may be quietly turning.

For investors, the message is to stay balanced. Avoid big currency bets, keep diversification broad, and watch how macro themes evolve. A measured hedging approach can protect against sudden AUD strength without forfeiting upside if global conditions weaken. An effective strategy will be one guided by data, not noise. The tea leaves rarely predict perfectly, but they reward those who pay attention.

1. Why does the Australian dollar move with commodity prices?

The Australian dollar tends to move with commodity prices because Australia is a major exporter of resources such as iron ore and coal. When global demand strengthens, commodity prices typically rise, increasing export revenues and supporting the currency. When demand weakens, the reverse can occur. While the relationship is not exact in the short term, it remains a consistent structural driver over time. 

2. Are interest rates still the main driver of currency movements?

Interest rates remain an important influence on currency movements, but their role has become less dominant for the Australian dollar. Historically, Australia’s higher yields supported the AUD, but that premium has narrowed in recent years. As a result, growth expectations, commodity trends, and broader risk sentiment now play a more prominent role in shaping currency direction. 

3. What does a range-bound Australian dollar mean for investors?

A range-bound Australian dollar generally signals that markets are waiting for clearer direction rather than pricing in a strong view on growth or policy. In this environment, large directional currency positions can be difficult to justify. A more measured approach - maintaining diversification and considering partial hedging - can help manage risk while preserving flexibility as conditions evolve. 

Speak to one of our advisers to learn more: paul.ashworth@cameronharrison.com.au

Sourced from:

Photo by iStock