Bank Hybrids in Australia: What the Phase-Out Means for Your Income

Investment Solutions | Market Insights
By Tristan Bowman, Partner
Bank hybrids have been a mainstay for income-seeking investors for over two decades. Their particular 'sweet spot' has been twofold: they have been ASX listed and available to retail and institutional investors, and they have carried a tax-effective grossed-up yield through imputation credits. Their removal represents a structural change in the Australian income market. The real question for investors is: where to for yield?
Posted 19 November 2026
  • The Australian Prudential Regulation Authority (APRA) has confirmed that Additional Tier 1 (AT1) capital instruments, known as bank hybrids, will be phased out of the Australian banking system, with the transition commencing from 1 January 2027 and completed by 2032. 

  • Existing hybrids will progressively reach their call dates. For investors, the key issue is the loss of a popular income instrument that has provided elevated yields, franking credits and direct access through the ASX. 

  • There is no single replacement for hybrids. Investors will need to consider Tier 2 bonds and a broader mix of fixed income securities, balancing yield, risk and liquidity. 

Hybrids, or AT1 capital, are designed to enhance the stability and resilience of banks. They act as a buffer to absorb losses when a bank's equity capital falls below a certain threshold. 

The name 'hybrid' stems from the ability for this capital to convert into equity in times of stress when the equity of a bank falls below a threshold. This 'tops up' a bank's equity to protect deposit holders. 

In this way, hybrids blend characteristics of both debt and equity. 

For over two decades, hybrids have offered investors elevated yields and franking credits unmatched by traditional fixed income. They became a mainstay for income-seeking investors, particularly in the high-net-worth segment. 

Hybrids have been popular investments for retail investors as: 

  • The franking credits distributed are highly tax effective, especially within varying tax environments such as superannuation. 

  • They have been effectively the only direct fixed income securities available on the ASX. 

  • They provide access to income-generating securities through a familiar listed market. 

The Australian hybrid market is relatively small at $43 billion, especially when compared with Government-issued bonds at over $1.5 trillion and financial institution bonds near $600 billion. 

The purpose of hybrids is to improve the stability of banks in times of stress. 

In the wake of Credit Suisse's collapse in 2023, APRA became increasingly concerned regarding the underlying investors in these hybrid securities. 

The Credit Suisse AT1 write-off showed that hybrids acted more as 'gone concern' rather than 'going concern' capital. APRA concluded that AT1s failed their intended purpose of absorbing losses early enough to stabilise banks in periods of stress. 

Of the $43 billion of hybrids in the market in Australia, APRA suggests that 53% are held by 'retail' or 'smaller' investors. In times of stress, the idea of converting hybrids to equity has given APRA concerns that imposing losses on these investors could bring contagion and political risk and undermine confidence in the system in a crisis. 

Other reasons for the change include: 

  • The collapse of Credit Suisse showed AT1 to be ineffective at stabilising a bank in a crisis. 

  • Removing AT1 simplifies the capital structure for banks. 

Under the new framework: 

  • Large banks' hybrid requirements, representing 1.5% of capital, will be replaced with 0.25% Common Equity Tier 1 and 1.25% Tier 2. 

  • Regional banks will replace AT1 entirely with Tier 2. 

  • Overall capital strength remains unchanged, but the composition becomes simpler, more transparent and more reliable. 

We understand APRA's positioning, though do not fully agree with its rationale. 

Hybrids do serve as a useful capital buffer pool within bank capital prudential regulation and, whilst maybe not well understood by retail investors, institutional investors do and can understand the hybrid instrument. 

We do not accept why hybrids could not be issued in the over-the-counter wholesale markets for the use of institutional and sophisticated investors who understand the risks of the instruments. 

Be that as it may, APRA has resolved its position and investors need to adapt. 

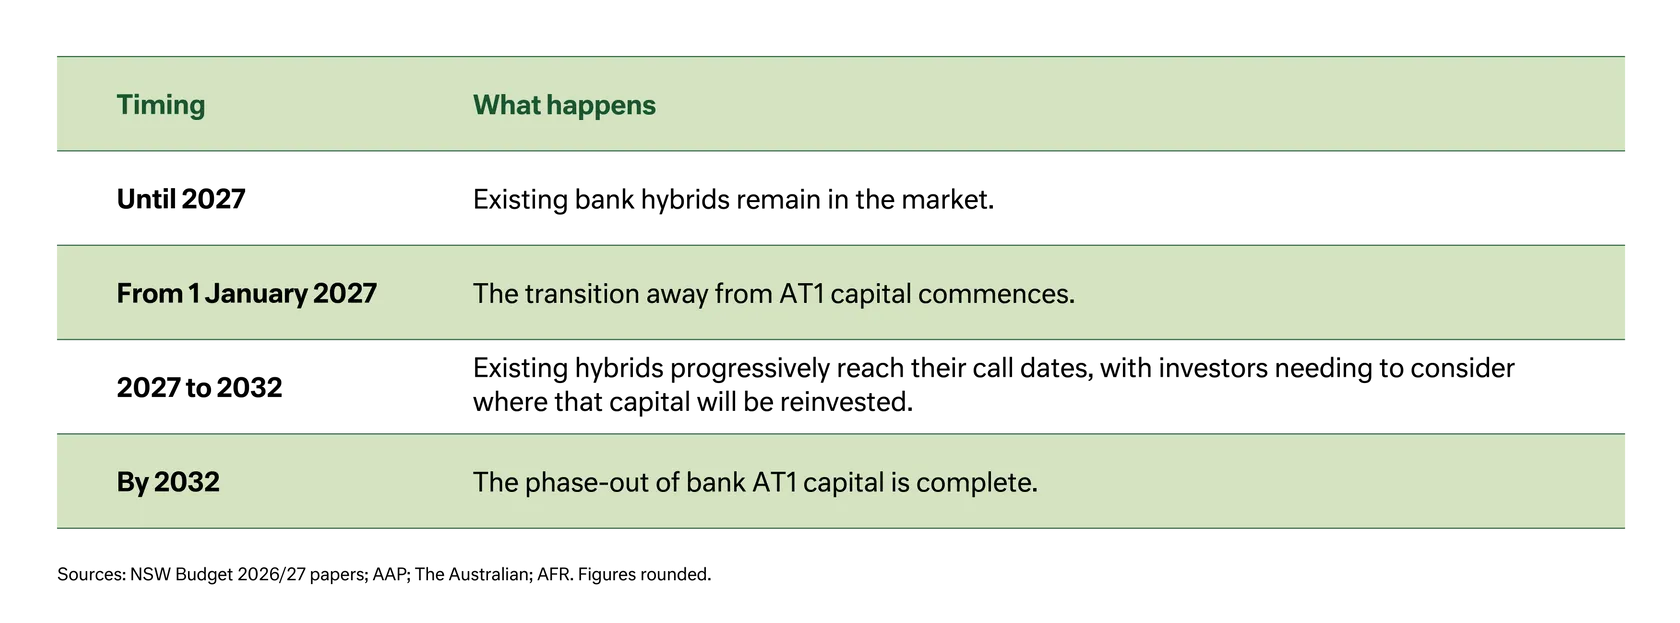
From 1 January 2027, hybrids will no longer qualify as regulatory capital, with the full phase-out completed by 2032. 

Table - what happends with bank hybrids, timings until 2027

The hybrid market historically provided a form of 'rollover certainty' at call dates, with new issues offering investors a simple reinvestment path. That mechanism will no longer exist. 

As hybrids mature, their prices will converge toward par, with no replacement issues to roll into. Investors must plan reinvestments ahead of call dates to avoid reinvestment risk and cash drag. 

Portfolio activity and discipline will therefore be more important in the years ahead. 

For investors, the phase-out has three important implications. 

1. The loss of franking credits

The most immediate adjustment is the loss of franking credits, which enhanced hybrid returns for many investors. 

The franking credits distributed by hybrids have been highly tax effective, especially within varying tax environments such as superannuation. 

Replacement strategies will therefore need to take account of the fact that many fixed income alternatives do not provide franking credits. 

General illustration of the franking effect 

Where a hybrid provides a cash distribution together with franking credits, those credits increase the grossed-up value of the income for an investor able to use them. 

A fixed income investment providing the same cash income without franking will therefore not provide the same grossed-up income. 

The impact will vary depending on the investor's tax position. 

2. The capital effect at the call date

As hybrids mature, their prices will converge toward par. 

Where securities are trading above or below their call value, this can create a capital effect as they approach their call dates. 

3. Reinvestment risk

The hybrid market historically provided investors with new issues into which capital could be reinvested. 

That mechanism will no longer exist. 

As hybrids mature, investors will need to plan reinvestments well ahead of call dates to avoid reinvestment risk and cash drag. 

Investors who once relied on hybrids will therefore need to adapt portfolios and look more broadly across the fixed income universe. 

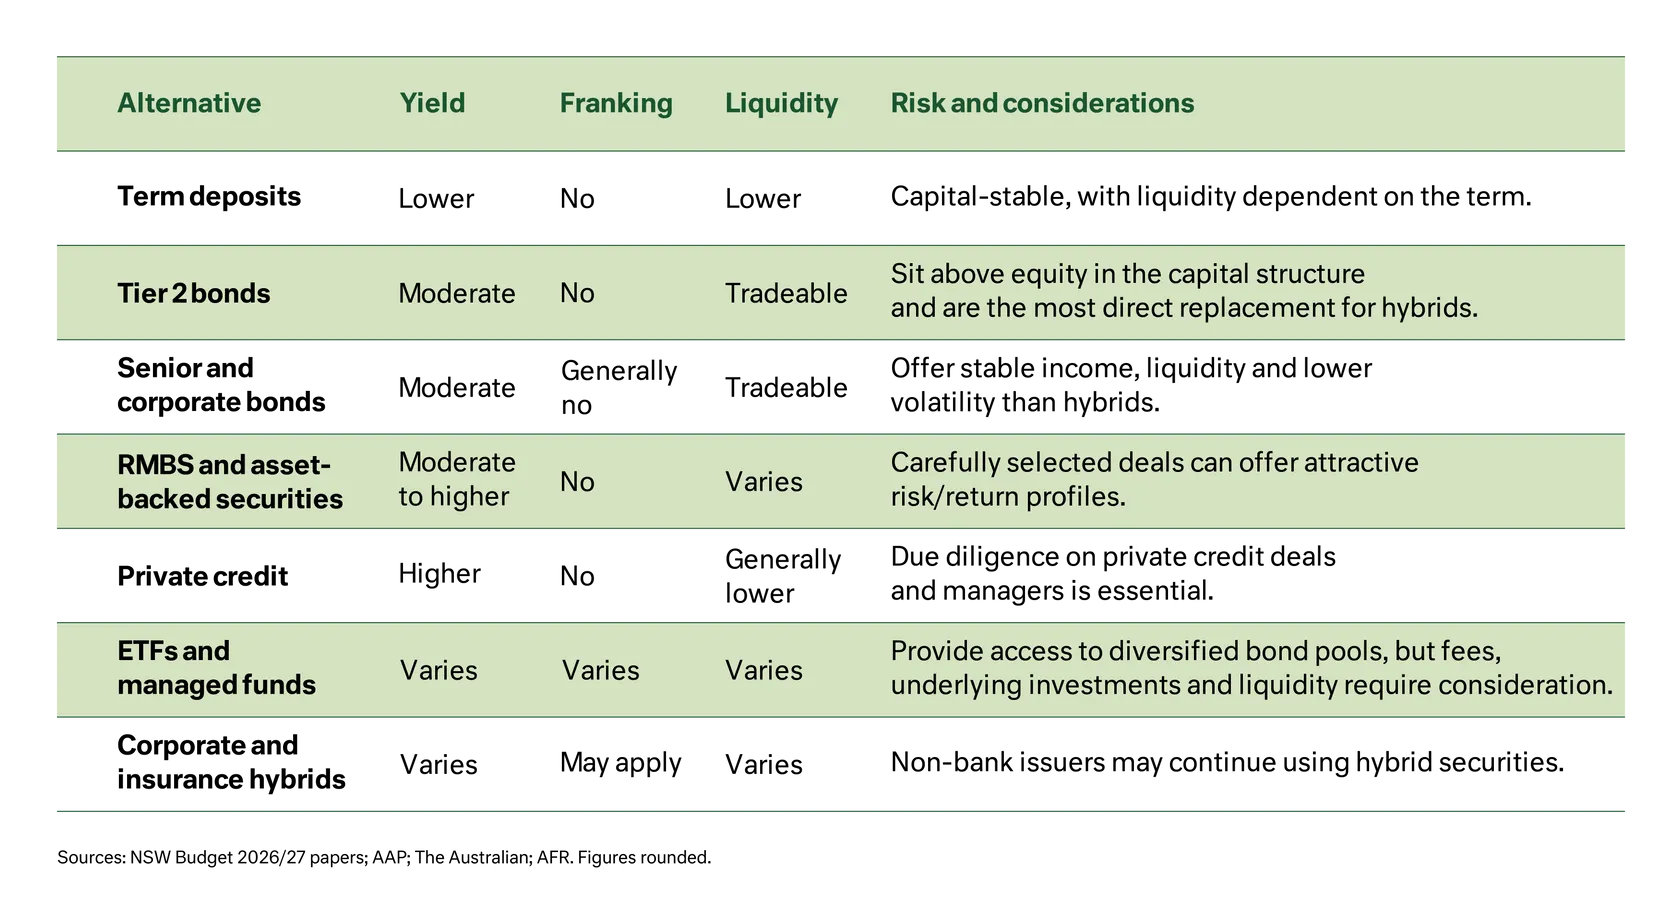
There is no single replacement for bank hybrids. 

The removal of hybrids encourages investors to look beyond banks and consider a broader, more diversified mix of income sources. 

Table - Your alneratives compared - bank hybrids

Tier 2 subordinated bonds will be the most direct replacement for hybrids. 

They pay mandatory coupons, sit above equity in the capital structure and are issued in large, tradeable sizes, though often in wholesale parcels which can exclude retail investors from directly investing on the ASX. 

Banks will be forced to issue more Tier 2 capital to replace the AT1. 

The query is, of the $43 billion invested into AT1 markets, how much of this flows into Tier 2? 

Senior and corporate bonds offer stable income, liquidity and lower volatility than hybrids. 

Kangaroo Bonds, being offshore bank issuance in AUD, can also broaden the fixed income universe. 

For increased yield, an option is the junior tranches of asset-backed securities, such as residential mortgage-backed securities (RMBS). 

Carefully selected deals can offer attractive risk/return profiles. 

Lenders of private capital demand higher interest rates to provide loans to those in the private market, despite in many cases the credit quality and security of the loan being high. 

Due diligence on private credit deals and managers is essential to get full transparency. 

With near-zero direct fixed income on the ASX, investors can gain exposure via products such as ETFs and managed funds. 

This can be an increased burden on the investor, with many products having layers of fees and a lack of transparency in underlying investments. It can be difficult to choose appropriate investments. 

Treasury departments of corporate issuers may see the demand for franking credit investments and issue corporate hybrids to diversify their funding base. 

Insurers are also permitted to continue utilising hybrid securities in their capital structures. 

Cameron Harrison's Fixed Income Strategies have held bank hybrid securities (AT1) for over 20 years. 

Notwithstanding APRA's phase-out of these capital instruments, their importance had already been diminishing within our Fixed Income Strategies over the last few years, particularly our Core Interest Income Strategy. 

The Core Interest Income Strategy is a highly diversified portfolio with over 85 individual positions, investing directly in investment-grade, highly liquid traded debt securities across subordinated bank debt, RMBS, ABS and covered bonds. 

By investing directly in individual issuer bonds, clients benefit from full transparency, accountability and flexibility. 

The strategy combines capital stability, reliable income and liquidity and can form a core component of balanced portfolios. 

With this regulatory change, various products are being brought to market to meet the needs of yield-conscious investors. It is important for investors not to be 'dazzled' by target yields, and instead rely on proper, independent due diligence that takes account of: 

  • security diversification; 

  • stress testing and volatility; 

  • liquidity terms; 

  • fees, both direct and indirect; and 

  • deed terms. 

Replacement strategies will require balance: 

  • Lower-risk Tier 2 bonds and senior credit for portfolio stability. 

  • Higher-yield private credit or niche corporates to offset income reductions. 

  • Liquidity planning through tradeable bonds and ETFs, complemented by carefully sized illiquid allocations. 

The removal of bank hybrids is not simply a regulatory shift. It is the end of a uniquely Australian income product. 

While hybrids blended debt and equity in a way that suited many investors, they also carried opaque risk. 

The new environment provides the opportunity to build multi-layered, actively managed portfolios that are more transparent, more resilient and more diversified. 

For high-net-worth investors, this is an opportunity to move beyond a single, bank-centric product and embrace a broader credit landscape that better aligns income needs with long-term stability, diversification, reduced volatility and improved liquidity. 
1. What are bank hybrids?

Bank hybrids, or Additional Tier 1 capital, are securities that combine characteristics of both debt and equity. They have traditionally provided investors with income and franking credits while acting as a buffer to absorb losses when a bank comes under financial stress. They have also been ASX listed, making them directly accessible to both retail and institutional investors. 

2. Why are bank hybrids being phased out in Australia?

APRA concluded that AT1 securities did not absorb losses early enough to stabilise banks during periods of stress. The experience of Credit Suisse in 2023, together with APRA's concerns about the significant proportion of hybrids held by retail and smaller investors, contributed to the decision to move towards a simpler bank capital structure. 

3. What can replace bank hybrids?

There is no single replacement for bank hybrids. Tier 2 subordinated bonds will be the most direct replacement within bank capital structures, while senior and corporate bonds, RMBS and other asset-backed securities, private credit, ETFs and managed funds, and corporate or insurance hybrids can provide alternative sources of income. Investors will need to balance yield, risk and liquidity. 

If bank hybrids form part of your income portfolio, we can review your existing holdings and consider how that income might be replaced as individual securities are called.

Speak to one of our advisers to learn more: tristan.bowman@cameronharrison.com.au

Sourced from:

Photo by iStock